Cashea Venezuela: How "En Cuotas Sin Interés" Shopping Works
Only about 7% of Venezuelans carry a credit card. Those who have one usually get a limit of maybe $60 a month, which won't cover a decent pair of shoes. And yet more than half the adults in the country now have a Cashea account. Funny how that works.
Cashea is a Venezuelan buy now, pay later finance app. Not a bank, just a mobile app on your phone. You pay part of the price, leave the store with your stuff, and pay off the rest in interest-free installments every 14 days. We'll get into the levels, the late fees, and the slightly odd question of how a lender makes money with zero interest.
What Is Cashea and Why Venezuela Needed It
Start with what happened to Venezuelan credit. In less than a decade, consumer lending shrank from roughly $16 billion to about $200 million. Hyperinflation ate the bolívar. Banks were stuck with brutal reserve requirements, so lending to households basically stopped, and the credit cards that survived have limits that look silly next to the price of a fridge.
Meanwhile the economy dollarized on its own. Shops put prices in US dollars. Salaries come in a mix of dollars and bolívares, and plenty of families keep savings in cash or stablecoins. People had money, sort of. What they didn't have was any way to pay for a big purchase over a few weeks.
Cashea showed up right there. Pedro Vallenilla, who had already built a deals site and a debt-collection company, launched it in Caracas a few years ago with a pretty blunt pitch. Walk into a store, scan a code, pay some now and the rest later. No interest, and no bank anywhere in the picture.
The numbers, according to the company:
- More than 10 million consumer accounts, over half of Venezuela's adult population
- A network of roughly 40,000 partner stores
- More than 100 million transactions since launch
Caracas Chronicles once estimated that about 1% of the country's GDP ran through the platform, and that was back when it had half the users it has today. Not many consumer apps, anywhere, got that deep into a national economy that fast.
How Cashea Works: Interest-Free Installments Every 14 Days
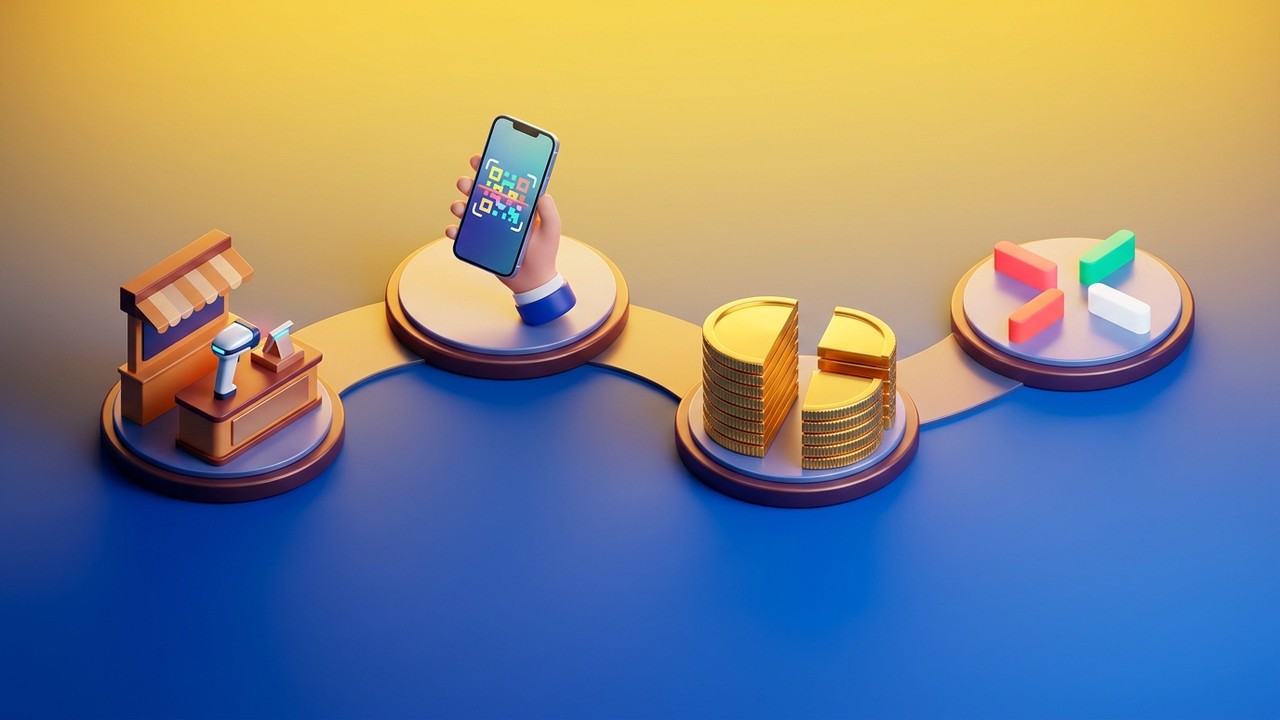
Sneakers or a washing machine, the mechanic doesn't change. Every Cashea purchase splits in two. There's the down payment, which locals call the inicial, and then the rest gets cut into equal cuotas, or installments. The tagline on the company's site says it in Spanish: "compra en cuotas sin interés." Buy in installments, pay no interest.
Here's roughly how it goes at the counter:
- Pick a product at a partner store or in the Cashea app's online catalog. Anything from $25 up works (or the bolívar equivalent at the official BCV rate).
- Choose Cashea at checkout. The cashier pulls up a QR code and you scan it.
- Pay the down payment. How much depends on your level, which we cover below. Cash, card, transfer, whatever the store takes.
- Receive the product. Most people just carry it out. Online orders get picked up or delivered.
- Pay the rest every 14 days. Equal chunks, two weeks apart, no interest.
Some quick math. You're new, so you're at Level 1, and you want a $200 microwave. Sixty percent up front means $120 at the register.
That leaves $80, and it turns into three payments of about $26.67, one every 14 days. Six weeks later the microwave is yours, and the total you paid is still exactly $200.
Prices show up in US dollars. You can still pay in bolívares at that day's rate, which is handy in a country where the official rate, the street rate and the stablecoin rate almost never agree.
Línea Principal vs Línea Cotidiana
You actually get two credit lines, not one. The Línea Principal (main line) is for the big stuff: a TV, a sofa, a new jacket. That gets split into three or more installments. Then there's the Línea Cotidiana, the everyday line, which people use at the supermarket or the pharmacy and pay back in one go two weeks later.
Why bother separating them? Because otherwise one big grocery run could eat the room you'd been keeping for a phone.
Download Cashea From Google Play or App Store and Sign Up
Getting started takes a few minutes, and you don't need a credit history or proof of income. The company relies on identity verification and its own scoring instead of a traditional bank check.
- Download the app. The mobile app is available on Google Play for Android and on the App Store for iPhone. It's free, and there's no subscription.
- Enter your contact details. You'll need an active email address and a Venezuelan mobile number.
- Verify your identity. Upload your cédula (Venezuelan national ID card) and take a selfie so the app can match your face to the document.
- Get your purchase line. Approval usually comes in a few minutes. Your línea de compra (purchase line) is the maximum balance you can have outstanding in installments after down payments.
New users start with a modest purchase line. Press reports have mentioned starting amounts in the range of $130 to $160, though the exact figure depends on the company's scoring and changes over time. Pay on time and it grows.
One practical limitation: because Cashea requires a Venezuelan ID and phone number, it isn't available to foreigners or to the Venezuelan diaspora shopping from abroad.
Club Cashea Más Levels and Your Purchase Line
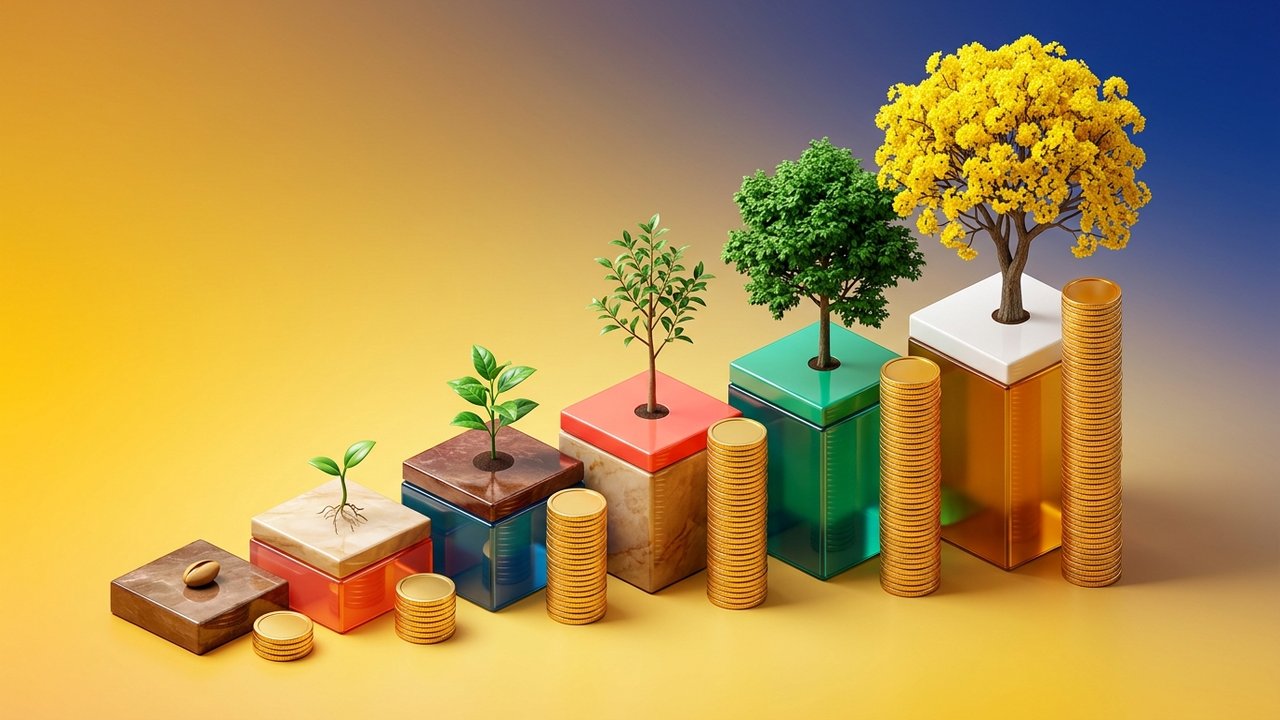
The company runs a loyalty program called Club Cashea Más. Every user starts at Level 1, and moving up lowers the down payment, raises the purchase line, and unlocks longer installment plans. The levels are named after stages of a tree's growth, ending with the araguaney, Venezuela's national tree.
According to the official Cashea website, the levels currently look like this:
| Level | Name | How to reach it | Down payment | Installments (main line) |
|---|---|---|---|---|
| 1 | Semilla (Seed) | Starting level | 60% | 3 |
| 2 | Raíz (Root) | 5 on-time payments or $120 in purchases | 50% | 3 |
| 3 | Hoja (Leaf) | 10 on-time payments or $400 in purchases | 40%, from 30% at select stores | Up to 12 |
| 4 | Tronco (Trunk) | 20 on-time payments or $800 in purchases | 40%, from 25% at select stores | Up to 12 |
| 5 | Árbol (Tree) | 40 on-time payments or $2,000 in purchases | 40%, from 20% at select stores | Up to 12 |
| 6 | Araguaney | 80 on-time payments or $4,000 in purchases | 40%, from 20% at select stores | Up to 12 |
Each step up adds 25% to your purchase line. At Level 6, your line is also recalculated every quarter. You earn points for every on-time payment, and the company says those points will be redeemable for coupons, promotions, and raffles.
Two caveats. First, the rules change. The company regularly runs campaigns, such as zero-down purchases for Level 6 users on everyday spending, and some older articles still quote a 50% down payment for Level 1. Always check the current terms in the app.
Second, levels can go down as well as up if you pay late.
In practice, Level 3 is where things change. Three installments become as many as twelve, and Cashea stops being a six-week payment plan. It starts to look more like a small consumer loan, just with no interest on it.
Where You Can Shop With Cashea: Stores and Online Orders
The service started with a couple dozen partner stores, mostly clothing and electronics brands. The network has since grown to tens of thousands of merchants across dozens of Venezuelan cities. You'll find Cashea in:
- Electronics and phone shops, including several international brands
- Home appliance and furniture stores
- Clothing, footwear, and sporting goods retailers
- Pharmacies and supermarkets (mainly through the everyday line)
- Opticians, auto parts shops, and beauty stores
You can also shop online inside the mobile app. Browse a partner's catalog, choose your installment plan, and pay the down payment through the app with Pago Móvil (Venezuela's interbank mobile transfer system), a bank transfer in bolívares, or a cash deposit. After the down payment is confirmed, the store contacts you by email to arrange pickup or home delivery, if it offers delivery.
There's no cap on the number of purchases you can make. The only limit is that the total of all your outstanding installments must fit within your purchase line.
Cashea Fees, Late Payments and Account Pauses
The main selling point is that the service costs nothing if you pay on time. There's no interest, no annual fee, and no charge to open an account. The costs show up only when you miss a payment.
Here is how late payments are handled, based on Cashea's help center:
- Grace period. You have a short window after the due date. If an installment is still unpaid two days later, a late fee applies.
- Late fee. Cashea charges $4 for each overdue installment.
- Blocked purchase line. While any installment is overdue, you can't make new purchases.
- Account pause and reactivation charge. If you skip a payment, pay late, or pay only part of an installment, the account is paused and you'll pay a reactivation fee to unlock it.
- Level drop. Repeated late payments can push you down to a lower level, which means a higher down payment and a smaller line.
Four dollars doesn't sound like much. On cheap items it adds up fast, though. Miss two installments of $10 each and you've paid $8 in penalties, which is 40% on top of the overdue amount.
Payments themselves go through the same local rails as down payments: Pago Móvil, bank transfers, or cash deposits. The app shows a calendar of upcoming installments and sends reminders, which helps, since a 14-day cycle comes around faster than most people expect.
How Cashea Makes Money and Who Is Behind It
If shoppers pay no interest, who pays? The merchants, who hand over a commission on each sale made through the app. Stores accept that cost because installments bring in customers who otherwise couldn't afford the purchase at all.
Reports from Venezuelan media have pointed to noticeably higher conversion rates at stores that offer Cashea.
Technically the merchant extends the credit and Cashea covers the default risk. For that to work, almost nobody can stop paying. So far, almost nobody has. The company has reported a non-performing loan rate below 2%. The low ticket sizes, short 14-day cycles, and the threat of losing access to the main way most Venezuelans can buy on credit keep repayment rates high.
The leadership team includes:
- Pedro Vallenilla, co-founder and CEO
- Ramón Lange, COO, previously at Rappi
- Nicolás Curat, CTO
- Arnoldo Gabaldón, CFO, formerly at McKinsey
Cashea recently raised $100 million across two rounds. A $40 million Series A, split between equity and debt, was led by Spice Expeditions, with Architect Capital providing the debt. A $60 million Series B followed, led by FinSight Ventures. The company says it will use the money to move beyond installments into payments, savings, and other financial services for consumers and businesses.
Is Cashea Safe? Pros and Cons of the Cashea App
It's a real, well-funded company with millions of active users, partnerships with major retailers, and listings on both official app stores. It isn't a scam. Whether it's a good fit for you is a separate question.
| Pros | Cons |
|---|---|
| No interest if you pay on time | Only available in Venezuela with a local ID |
| Approval in minutes, no credit history needed | High down payment (60%) at the entry level |
| Huge network of partner stores | $4 late fee per installment, plus reactivation charges |
| Lets you build a payment track record | 14-day cycles leave little room for missed paydays |
| Prices in dollars, payable in bolívares | Easy to overspend across multiple purchases |
| Up to 12 installments at higher levels | Rules and promotions change often |
The real risk sits with the user, same as with any buy now, pay later service: small installments make big purchases feel cheap, and several overlapping plans can add up to more than one paycheck can handle. A good rule is to keep total installments due in any two-week period well below what you can actually spare.
On the data side, Cashea asks for sensitive information, including your ID and a selfie. Download the app only from Google Play or the App Store, and never share your login codes with anyone who contacts you claiming to be from the company.
Alternatives to Cashea, Including Stablecoin Payments
Cashea dominates Venezuelan BNPL, but it isn't the only way to spread out or simplify a purchase. Here are the main alternatives to Cashea:
- Krece. A financing service focused on smartphones. You pay for a phone in installments, and the phone itself is the collateral. It also operates in the Dominican Republic and Peru.
- In-store credit. Some larger retailers and appliance chains offer their own layaway or installment plans, usually with stricter approval.
- Bank credit cards. They still exist, but low limits make them impractical for anything beyond small purchases.
- Stablecoins. USDT, often called the "Binance dollar" locally, has become a common way to save and pay in Venezuela. With the IMF projecting triple-digit inflation, many people hold their savings in dollar-pegged tokens and use them for everyday purchases, rent, and salaries.
That last point matters for businesses outside Venezuela. If you run an online store, a SaaS product, or a freelance service with Venezuelan customers, local card networks and bank transfers are hard to use from abroad. Plenty of those customers already hold USDT and would rather pay in it than chase a working international card.
Taking stablecoins gets around that, and the buyer doesn't need to open anything new. A crypto payment gateway lets you take USDT and other coins at checkout, then convert or keep the funds as you prefer. If that fits your business, Plisio supports stablecoin and crypto payments with simple plugins for popular e-commerce platforms.
Cashea answered a very local problem: a dollarized economy with almost no consumer credit. For Venezuelans, it has become the default way to buy a phone, a fridge, or a week's groceries in parts. Outside the country, it's a useful case study in what happens when banks pull back and an app moves into the space.