Shakepay Explained: How to Buy Bitcoin in Canada and Earn Crypto
Ask a Canadian where they bought their first bitcoin and there's a decent chance the answer is Shakepay. It's a Montreal app. You can buy and sell bitcoin and ether with it, send cash to a friend, and pick up a few free sats just for opening it each morning. No altcoins. No trading terminal with twenty indicators. No leverage. Weirdly, that's the selling point.
So what's actually under the hood? I'll go through how the platform works, how safe it is, the real cost of a trade (it isn't zero), ShakingSats, the Shakepay Card, and the stuff people complain about on Reddit. Thinking of signing up, or already have the app and never read the fine print? Either way, this should help.
What Is Shakepay and How Does the Platform Work
Two guys from Montreal, Jean Amiouny and Roy Breidi, started the company back in 2015. Their first idea was a prepaid card you'd top up with bitcoin and then use at a normal store. It didn't really take off. By 2018 they'd turned it into the thing everyone knows now, an app where you swap Canadian dollars for bitcoin in a couple of taps.
Crypto went mainstream after that, and money followed: a $44 million Series A in early 2022. Shakepay now claims more than 1.4 million users here, in a country of roughly 40 million. That is a lot of people shaking their phones.
One thing trips people up. Shakepay is a broker, not an open crypto exchange. There's no order book and you're not trading against other people. You see a price, hit buy, and the company sells you coins from its own inventory. Easy. But that price has a markup baked in, and I'll get to it in the fees part.
| Feature | Details |
|---|---|
| Founded | 2015, Montreal, Quebec |
| Supported assets | Bitcoin (BTC) and Ether (ETH) |
| Availability | Canadian residents in every province and territory |
| Funding | Interac e-Transfer, wire transfer, direct deposit, crypto |
| Trading model | Broker with a built-in spread, no commission |
| Card | Visa card with bitcoin cashback |
| Regulation | FINTRAC, provincial securities regulators, CIRO |
Want Solana? XRP? Some dog coin? Not here. The founders have been pretty blunt that adding hundreds of tokens just isn't their thing, so you'd need another crypto exchange for that.
Is Shakepay Safe? Regulation, Custody and Scammer Risks
Safety is the most common question about any crypto app, and on paper this one checks out well:
- FINTRAC registration. Shakepay is registered as a money services business with Canada's financial intelligence agency, which means it must follow anti-money-laundering and KYC rules.
- Restricted dealer status. In 2023 the company received registration as a restricted dealer with the Canadian Securities Administrators, including Quebec's AMF, covering all provinces and territories.
- CIRO membership. In early 2025 the company became a member of the Canadian Investment Regulatory Organization as an investment dealer. It was the first crypto platform based in Quebec to do so.
- CIPF coverage for cash. Thanks to CIRO membership, cash balances are covered by the Canadian Investor Protection Fund up to $1 million CAD. Crypto holdings are not covered by CIPF.
- Cold storage and 2FA. Most customer crypto is held offline, and accounts can be protected with an authenticator app.
It is not a bank, though. No interest on your CAD balance, no CDIC insurance.
In practice, scammers are a bigger threat than the platform. Fake "support agents" show up in Reddit threads and Discord servers, and phishing texts pretend to come from Shakepay. A simple rule protects you from most of it: real staff will never ask for your 2FA code, your password, or a wallet recovery phrase. If someone reaches out to you first and asks for any of those, it's a scam.
How to Use Shakepay: Account Setup and First Purchase
Getting started takes about ten minutes of active time, plus whatever the verification queue adds. To use Shakepay from scratch:
- Download the app. It's available on iOS and Android, and there's a web version for desktop.
- Create your Shakepay account. Enter your email, phone number and a strong password, then turn on two-factor authentication right away.
- Complete KYC. You'll upload a government-issued ID and take a selfie. Most people are approved the same day, but it can take a day or two during busy periods.
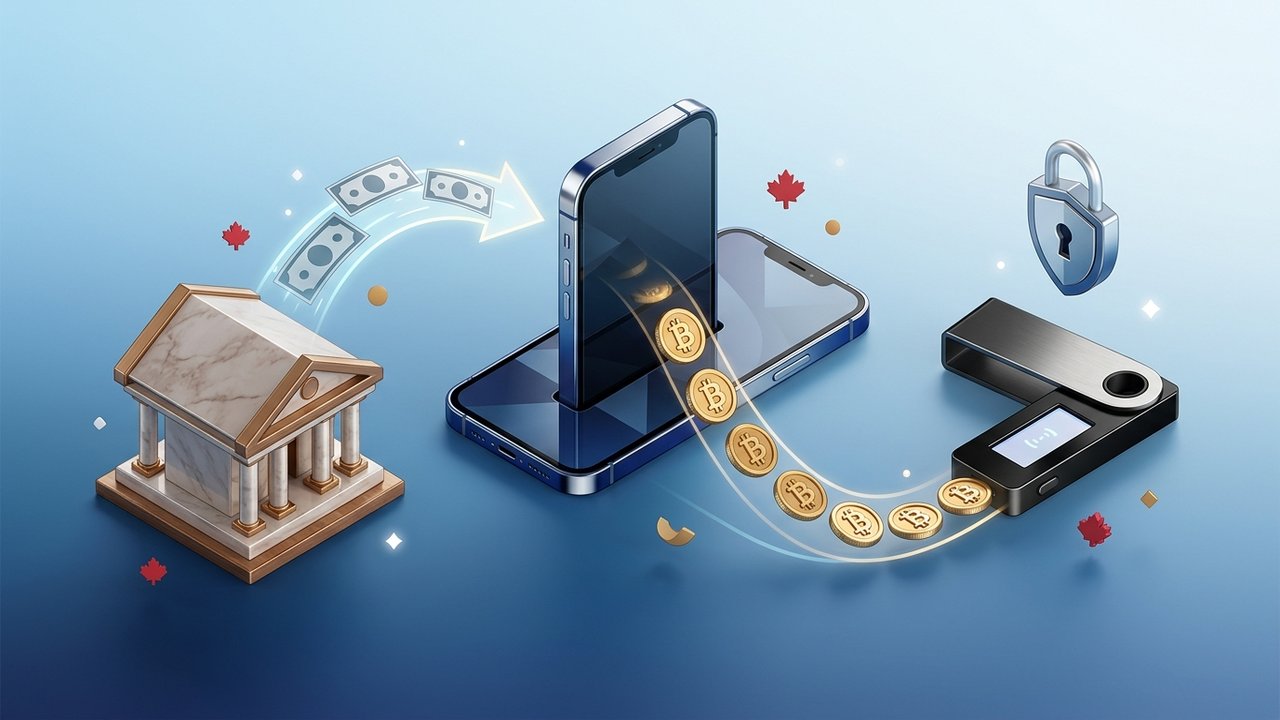
- Fund your balance. Send an Interac e-Transfer from your bank to the address shown in the app. The money usually arrives within minutes.
- Buy bitcoin or ether. Choose the amount in CAD, check the quoted price, and confirm. The crypto lands in your in-app wallet instantly.
- Decide where to keep it. You can leave it in the app or send BTC to your own hardware wallet for self-custody.
One limitation catches people off guard: the platform is only for Canadian residents. It doesn't work in the USA, and you can't open an account with a foreign address.
Plenty of people who buy bitcoin regularly just do small recurring purchases and stop trying to time the market. Boring, but it works for them.
How to Fund a Shakepay Account and Withdraw CAD
Interac e-Transfer is the main way money moves in and out of the app, and for most users it's the only method they'll ever need. Limits depend on your account history, so treat the numbers below as typical ranges at the time of writing and check the app for your own.
| Method | Typical minimum | Typical maximum | Speed | Fee |
|---|---|---|---|---|
| Interac e-Transfer (deposit) | $5 | $10,000 per transfer | Minutes | Free |
| Interac e-Transfer (withdrawal) | — | Around $5,000 per transfer | Minutes to a few hours | Free |
| Wire transfer | $5,000 | No set maximum | 1–3 business days | Bank fees may apply |
| Direct deposit (paycheque) | — | — | Payday | Free |
| Crypto deposit (BTC/ETH) | Network-dependent | — | Network confirmations | Network fee |
About direct deposit: you can route all or part of your paycheque straight into your balance, a feature the company calls getting "shakepaid." It's also one of the ways to unlock better card reward tiers.
Taking money out? Sell your crypto into your CAD balance, choose to withdraw, and send an Interac e-Transfer to your bank. Most withdrawals arrive quickly, though larger ones or first-time transfers can stay pending while they're reviewed.
Shakepay Fees: Spread, Commission and Real Costs
Shakepay advertises commission-free trading. Technically true. There's no line item that says "fee" when you buy. Interac deposits and withdrawals are free too.
The cost lives in the spread, which is the gap between the market price and the price the app quotes you. The company has said it targets a spread of roughly 0.5% to 2% over its benchmark price, and that spread can widen when markets get volatile or liquidity dries up.
Say you buy $1,000 of bitcoin and the effective spread is about 1.5%.
You receive roughly $985 worth of BTC at market value. If you sell right away, you pay a spread again on the way out. A round trip can cost you 3% or more.
| Cost type | Amount | When it applies |
|---|---|---|
| Trading commission | $0 | Never |
| Spread | ~0.5%–2%, wider in volatile markets | Every buy and sell |
| Interac e-Transfer | Free | Deposits and withdrawals |
| On-chain withdrawal | Network fee | Sending BTC or ETH out |
| Card FX markup | Depends on reward status | Purchases in foreign currency |
Want to see the spread yourself? Open the app and compare the buy price with the sell price for the same asset at the same moment. The gap between them is roughly double the one-way markup.
For a $50 buy now and then, who cares. For larger sums, compare the effective cost across a few Canadian crypto platforms before you commit.
ShakingSats and Shake Squads: Earn Bitcoin Daily
ShakingSats is the feature that made Shakepay famous. Once a day you open the app and physically shake your phone, and you receive a small amount of bitcoin. "Sats" is short for satoshis, the smallest unit of BTC.
How it works:
- Streaks matter. The longer your daily streak, the more sats you receive per shake. Miss a day and the streak resets.
- Eligibility depends on activity. The company has tightened the rules over time. Keeping full access usually requires ongoing activity such as card spending, direct deposits or regular trades.
- Shake Squads add a group bonus. You join a squad with other users, and when members spend with their card, everyone in the squad earns extra sats.
- Amounts are small. Think of it as a few sats a day that slowly stack up, not a source of income.
Reddit is split on it. Long-time users often say the daily amounts have shrunk, and some find it hard to join an active shake squad. Others still enjoy the habit because it builds a small BTC balance without spending anything.
There's also a tax angle. In Canada, rewards like these may count as income at their fair market value when you receive them. Keep your transaction history and talk to an accountant if your rewards add up.
The Shakepay Card: Bitcoin Cashback on Everyday Spending
The card is a Visa. You pay for groceries or gas out of your CAD balance and a slice comes back to you as bitcoin. No annual fee. Tap it at the store, or add it to Apple Pay or Google Pay and leave the plastic at home.
How much you get back depends on your "reward status" for the month, and honestly this part has changed a few times. Here's how third-party reviewers describe it right now:
| Reward status | BTC cashback | Foreign exchange markup | How to qualify |
|---|---|---|---|
| Base | 1% | Around 3% | Default for all users |
| Bright | 1% | Around 1.5% | Monthly exchange activity or direct deposit |
| Blue | 1.5% | 0% | Higher monthly direct deposit or trading activity |
Your tier resets monthly. Stop depositing or trading and you slide back down. Every so often there's a promo that bumps the rate for a while too.
For years the card only existed on your phone. Then came a waitlist for a physical one, and it's been going out to people in batches.
Oh, and the cashback lands as BTC, not dollars. Bitcoin dips 20%, your rewards dip 20%. Some folks love that, some hate it.
Shakepay Pros and Cons for Canadian Crypto Users
The short version:
| Pros | Cons |
|---|---|
| Very simple app, good for beginners | Only BTC and ETH supported |
| Free Interac e-Transfers in and out | Spread isn't shown as a clear percentage |
| Registered with FINTRAC and CIRO | Canadian residents only |
| Free daily sats through ShakingSats | No advanced trading tools |
| Bitcoin cashback card with no annual fee | No interest on CAD or crypto balances |
| Withdrawals to your own hardware wallet | Support by chat and email only, no phone line |
Shakepay fits people who want bitcoin exposure without complexity: first-time buyers, small regular savers, and anyone who likes earning BTC through everyday spending. Active traders, altcoin investors and users who want detailed tax reporting tools often look at broader platforms, such as Wealthsimple or larger exchanges, alongside it.
Accepting Crypto for Your Business Beyond Shakepay
Here's the catch for business owners. The app is made for regular people: you buy, hold, send and spend bitcoin. It won't help a shop take crypto from hundreds of customers.
Say you sell sneakers online, or run a small SaaS, or do freelance design. You'd want invoices that freeze the price for a few minutes. A WooCommerce or Shopify plugin. Stablecoins, since lots of buyers would rather pay in USDT than BTC. And maybe auto-conversion, so a bad day in the market doesn't wipe out your margin.
That's what a crypto payment gateway does. Your customer pays from any wallet (a Shakepay wallet works fine), and the gateway checks the payment, logs it and settles it to you. If that's what you're after, take a look at Plisio. It has plugins, invoicing and a long list of supported coins.
Is Shakepay Worth Using to Buy Bitcoin in Canada?
For a first bitcoin buy in Canada? Shakepay is about as painless as it gets, roughly the same effort as sending an e-Transfer to your roommate. It's properly regulated, Interac funding costs nothing, and you get a bit of free BTC on the side.
Would I park a big pile of money there and trade it every week? Probably not. The spread eats you on size, there are only two coins, and the rewards keep getting tweaked. My take: use it for what it does well, move long-term coins to your own wallet once you're comfortable, and always check what price you're really paying.